Documents / Credit Union SA
Financial services and credit disclosures
Issuer brochure BRC 1028 includes the procedure for complaints and external dispute resolution.
Issuer edition · 24 July 2025
Page 1 of 3
Full-size page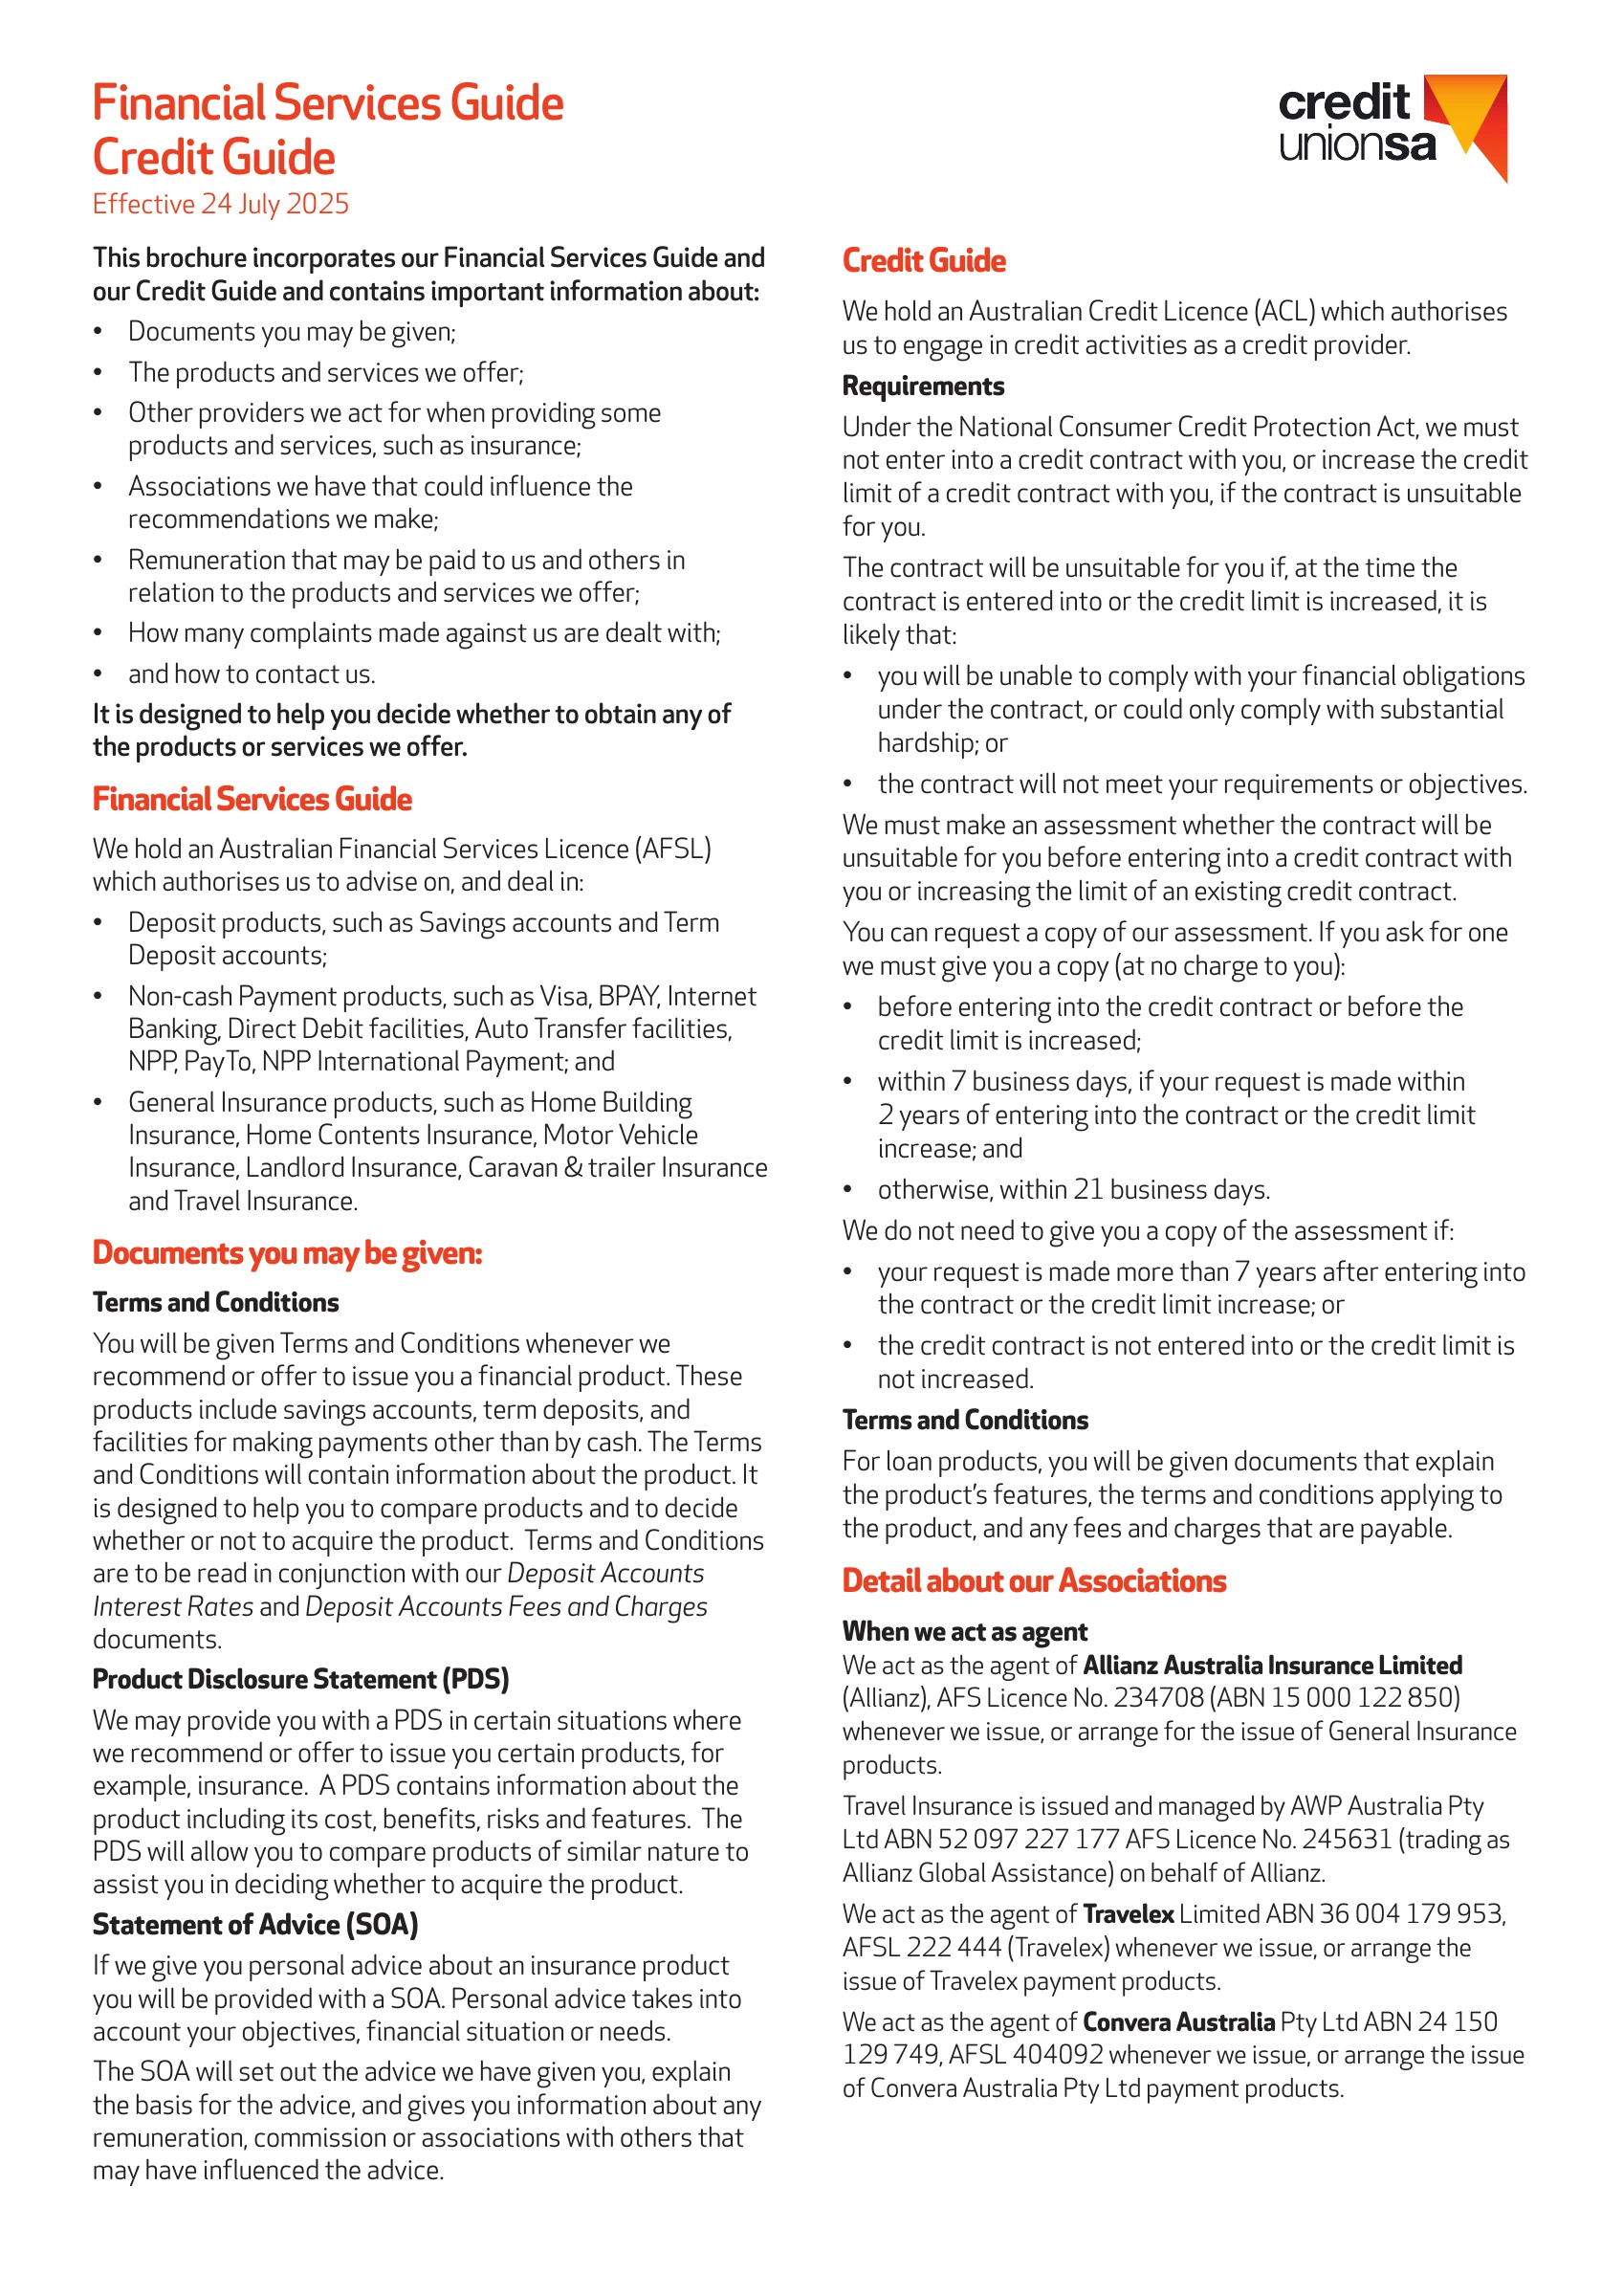
Read page text
Financial Services Guide Credit Guide Effective 24 July 2025 This brochure incorporates our Financial Services Guide and our Credit Guide and contains important information about: • Documents you may be given; • The products and services we offer; • Other providers we act for when providing some products and services, such as insurance; • Associations we have that could influence the recommendations we make; • Remuneration that may be paid to us and others in relation to the products and services we offer; • How many complaints made against us are dealt with; • and how to contact us. It is designed to help you decide whether to obtain any of the products or services we offer.
Credit Guide
Financial Services Guide
• the contract will not meet your requirements or objectives.
We hold an Australian Financial Services Licence (AFSL) which authorises us to advise on, and deal in: • Deposit products, such as Savings accounts and Term Deposit accounts; • Non-cash Payment products, such as Visa, BPAY, Internet Banking, Direct Debit facilities, Auto Transfer facilities, NPP, PayTo, NPP International Payment; and • General Insurance products, such as Home Building Insurance, Home Contents Insurance, Motor Vehicle Insurance, Landlord Insurance, Caravan & trailer Insurance and Travel Insurance.
Documents you may be given: Terms and Conditions You will be given Terms and Conditions whenever we recommend or offer to issue you a financial product. These products include savings accounts, term deposits, and facilities for making payments other than by cash. The Terms and Conditions will contain information about the product. It is designed to help you to compare products and to decide whether or not to acquire the product. Terms and Conditions are to be read in conjunction with our Deposit Accounts Interest Rates and Deposit Accounts Fees and Charges documents. Product Disclosure Statement (PDS) We may provide you with a PDS in certain situations where we recommend or offer to issue you certain products, for example, insurance. A PDS contains information about the product including its cost, benefits, risks and features. The PDS will allow you to compare products of similar nature to assist you in deciding whether to acquire the product.
Statement of Advice (SOA) If we give you personal advice about an insurance product you will be provided with a SOA. Personal advice takes into account your objectives, financial situation or needs. The SOA will set out the advice we have given you, explain the basis for the advice, and gives you information about any remuneration, commission or associations with others that may have influenced the advice.
We hold an Australian Credit Licence (ACL) which authorises us to engage in credit activities as a credit provider. Requirements Under the National Consumer Credit Protection Act, we must not enter into a credit contract with you, or increase the credit limit of a credit contract with you, if the contract is unsuitable for you. The contract will be unsuitable for you if, at the time the contract is entered into or the credit limit is increased, it is likely that: • you will be unable to comply with your financial obligations under the contract, or could only comply with substantial hardship; or We must make an assessment whether the contract will be unsuitable for you before entering into a credit contract with you or increasing the limit of an existing credit contract. You can request a copy of our assessment. If you ask for one we must give you a copy (at no charge to you): • before entering into the credit contract or before the credit limit is increased; • within 7 business days, if your request is made within 2 years of entering into the contract or the credit limit increase; and • otherwise, within 21 business days. We do not need to give you a copy of the assessment if: • your request is made more than 7 years after entering into the contract or the credit limit increase; or • the credit contract is not entered into or the credit limit is not increased. Terms and Conditions For loan products, you will be given documents that explain the product’s features, the terms and conditions applying to the product, and any fees and charges that are payable.
Detail about our Associations When we act as agent We act as the agent of Allianz Australia Insurance Limited (Allianz), AFS Licence No. 234708 (ABN 15 000 122 850) whenever we issue, or arrange for the issue of General Insurance products. Travel Insurance is issued and managed by AWP Australia Pty Ltd ABN 52 097 227 177 AFS Licence No. 245631 (trading as Allianz Global Assistance) on behalf of Allianz. We act as the agent of Travelex Limited ABN 36 004 179 953, AFSL 222 444 (Travelex) whenever we issue, or arrange the issue of Travelex payment products. We act as the agent of Convera Australia Pty Ltd ABN 24 150 129 749, AFSL 404092 whenever we issue, or arrange the issue of Convera Australia Pty Ltd payment products.
Page 2 of 3
Full-size page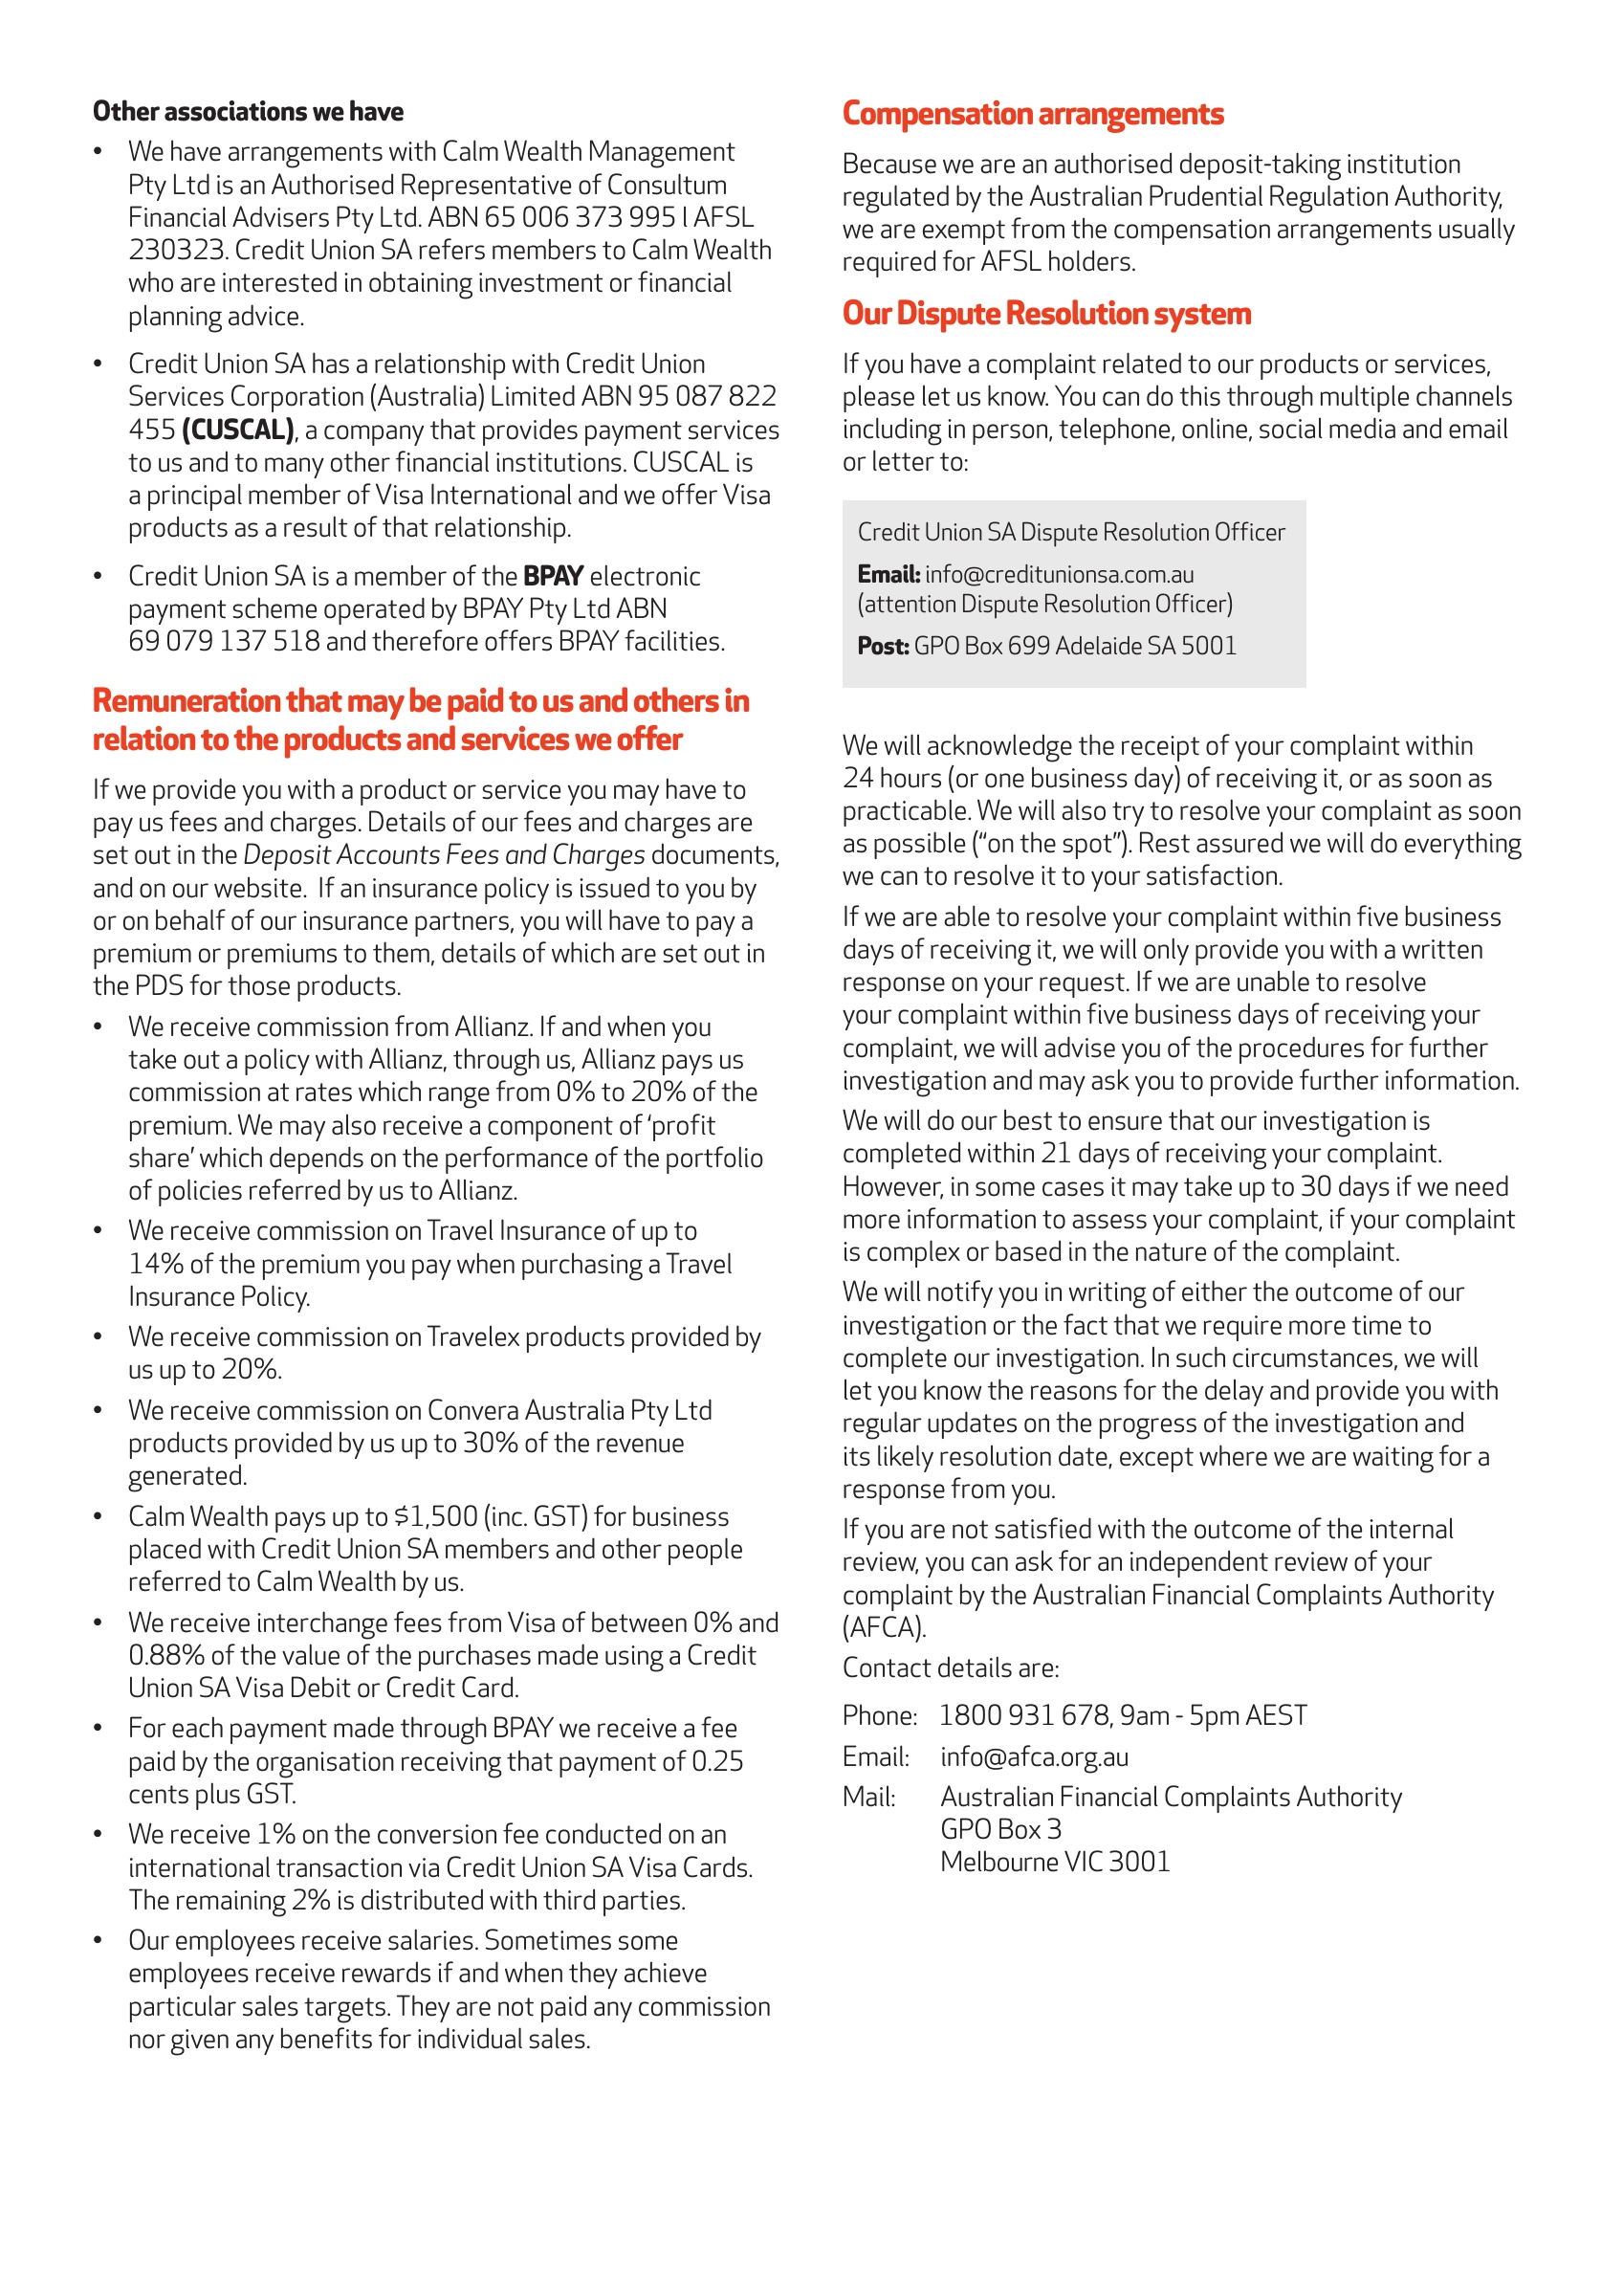
Read page text
Other associations we have • We have arrangements with Calm Wealth Management Pty Ltd is an Authorised Representative of Consultum Financial Advisers Pty Ltd. ABN 65 006 373 995 l AFSL 230323. Credit Union SA refers members to Calm Wealth who are interested in obtaining investment or financial planning advice.
Compensation arrangements
• Credit Union SA has a relationship with Credit Union Services Corporation (Australia) Limited ABN 95 087 822 455 (CUSCAL), a company that provides payment services to us and to many other financial institutions. CUSCAL is a principal member of Visa International and we offer Visa products as a result of that relationship.
If you have a complaint related to our products or services, please let us know. You can do this through multiple channels including in person, telephone, online, social media and email or letter to:
• Credit Union SA is a member of the BPAY electronic payment scheme operated by BPAY Pty Ltd ABN 69 079 137 518 and therefore offers BPAY facilities.
Email: info@creditunionsa.com.au (attention Dispute Resolution Officer)
Remuneration that may be paid to us and others in relation to the products and services we offer If we provide you with a product or service you may have to pay us fees and charges. Details of our fees and charges are set out in the Deposit Accounts Fees and Charges documents, and on our website. If an insurance policy is issued to you by or on behalf of our insurance partners, you will have to pay a premium or premiums to them, details of which are set out in the PDS for those products. • We receive commission from Allianz. If and when you take out a policy with Allianz, through us, Allianz pays us commission at rates which range from 0% to 20% of the premium. We may also receive a component of ‘profit share’ which depends on the performance of the portfolio of policies referred by us to Allianz. • We receive commission on Travel Insurance of up to 14% of the premium you pay when purchasing a Travel Insurance Policy. • We receive commission on Travelex products provided by us up to 20%. • We receive commission on Convera Australia Pty Ltd products provided by us up to 30% of the revenue generated. • Calm Wealth pays up to $1,500 (inc. GST) for business placed with Credit Union SA members and other people referred to Calm Wealth by us. • We receive interchange fees from Visa of between 0% and 0.88% of the value of the purchases made using a Credit Union SA Visa Debit or Credit Card. • For each payment made through BPAY we receive a fee paid by the organisation receiving that payment of 0.25 cents plus GST. • We receive 1% on the conversion fee conducted on an international transaction via Credit Union SA Visa Cards. The remaining 2% is distributed with third parties. • Our employees receive salaries. Sometimes some employees receive rewards if and when they achieve particular sales targets. They are not paid any commission nor given any benefits for individual sales.
Because we are an authorised deposit-taking institution regulated by the Australian Prudential Regulation Authority, we are exempt from the compensation arrangements usually required for AFSL holders.
Our Dispute Resolution system
Credit Union SA Dispute Resolution Officer
Post: GPO Box 699 Adelaide SA 5001
We will acknowledge the receipt of your complaint within 24 hours (or one business day) of receiving it, or as soon as practicable. We will also try to resolve your complaint as soon as possible (“on the spot”). Rest assured we will do everything we can to resolve it to your satisfaction. If we are able to resolve your complaint within five business days of receiving it, we will only provide you with a written response on your request. If we are unable to resolve your complaint within five business days of receiving your complaint, we will advise you of the procedures for further investigation and may ask you to provide further information. We will do our best to ensure that our investigation is completed within 21 days of receiving your complaint. However, in some cases it may take up to 30 days if we need more information to assess your complaint, if your complaint is complex or based in the nature of the complaint. We will notify you in writing of either the outcome of our investigation or the fact that we require more time to complete our investigation. In such circumstances, we will let you know the reasons for the delay and provide you with regular updates on the progress of the investigation and its likely resolution date, except where we are waiting for a response from you. If you are not satisfied with the outcome of the internal review, you can ask for an independent review of your complaint by the Australian Financial Complaints Authority (AFCA). Contact details are: Phone: 1800 931 678, 9am - 5pm AEST Email: info@afca.org.au Mail: Australian Financial Complaints Authority GPO Box 3 Melbourne VIC 3001
Page 3 of 3
Full-size page
Read page text
Customer Owned Banking Code of Practice The relevant provisions of the Customer Owned Banking Code of Practice (the Code) apply to all Credit Union SA products and services. The Code clearly sets out both your rights as a customer and our responsibilities as your financial institution in relation to service, advice and charges. You can download a copy of the Customer Owned Banking Code of Practice from: creditunionsa.com.au/legal/privacy
Want to know more about Credit Union SA or any of our products or services? We’d be delighted to help. Visit our website creditunionsa.com.au
Call us on
Visit us at 400 King William St, Adelaide SA 5000
Have a Mobile Lending Manager visit you
13 8777
Credit Union SA Ltd ABN 36 087 651 232 AFSL/Australian Credit Licence 241066 Credit Union SA Centre, Level 3 400 King William Street Adelaide SA 5000 GPO Box 699 Adelaide SA 5001 BRC_1028 202507024